We use cookies to improve your experience. By using BondbloX, you agree to our use of cookies.
Bond Market News
UST 10Y Approaches 5.3%
October 1, 2026

The long end of the US Treasury yield curve rose by 5-6bp, with the 10Y closing at 5.28%, levels last seen in 2002. On the data front, headline PCE inflation eased to 3.4% YoY from 3.7%, below expectations of 3.7%, while Core PCE slowed to 3.0% from 3.3%. US Q2 GDP growth was revised higher to 2.2% from 1.5%, while ADP Employments rose by 90k in September, above expectations of 75k. Personal spending increased 0.9% in August, in-line with estimates. Separately, Minneapolis Fed President Neel Kashkari said further rate hikes may be needed depending on how the economy evolves, with inflation still running too high. He noted that the broader economy remains resilient, supported by strong corporate profits, low unemployment and limited layoffs, although housing remains under pressure.
Looking at equity markets, the S&P closed lower by 0.3% while Nasdaq ended higher by 0.2%. US IG CDS spreads were 0.8bp wider, while HY CDS spreads widened by 4.2bp. European equity markets ended lower. European IG CDS spreads were 0.1bp wider, and Crossover spreads were flat. Asian equity markets have opened broadly higher this morning. Asia ex-Japan CDS spreads tightened by 0.3bp.
Rating Changes
- Delhi International Airport Ltd. Upgraded To ‘BB+’ On Improved Regulatory Environment; Outlook Positive
- GMR Hyderabad International Airport Upgraded To ‘BBB-‘ On Improving Regulations And Financials; Outlook Stable
- Moody’s Ratings upgrades Bolivia’s ratings to Caa2, maintains positive outlook
- Moody’s Ratings upgrades China Merchants Ports to A3 from Baa1; outlook stable
- Moody’s Ratings downgrades Cornerstone’s CFR to Caa3, outlook negative
- Ibercaja Banco S.A. Outlook Revised To Positive On Strengthening Capitalization; ‘BBB/A-2’ Ratings Affirmed
- Fitch Affirms Volkswagen AG at ‘A-‘; Outlook Negative
Term of the Day: Amend and Extend
Amend and Extend is a debt/loan market jargon referring to a strategy where issuers negotiate with lenders to extend the maturity date of part of an existing loan facility instead of selling new high-yield debt for refinancing purposes. Lenders negotiate for higher fees and interest rate margins to be compensated for the delay by issuers. Bloomberg notes that junk-rated companies use this “amend and extend” tactic to continue their existing deals without having to refinance at much higher yields.
Talking Heads
On Pace of Bond Selloff Key for Stocks – Oppenheimer, Goldman Sachs
“The real issue is whether we get a further sharp selloff in bond markets from here, and in that context, I think equities become vulnerable,… If we were to get further rises in bond yields, and importantly, if that happens very quickly, because we found in the past it’s not just the levels but the speed of adjustment and indeed the reasons, it’s going to have some impact on equities.”
On Global Bonds See Worst Quarter Since 2024 on Inflation Fear – Michael Every, Rabobank
“The third quarter didn’t just drop hopes of ‘lower for longer,’ but doused them in scarce diesel and set fire to them”
On Gilt Market Faces Growing Spillover Risks – Bank of England
“Although hedge fund leverage in the gilt market has been stable, it remains elevated, and deeper interconnections between vulnerabilities means the risk of a sharp adjustment persists,… This underlines the importance of the Bank’s work on gilt repo market resilience.”
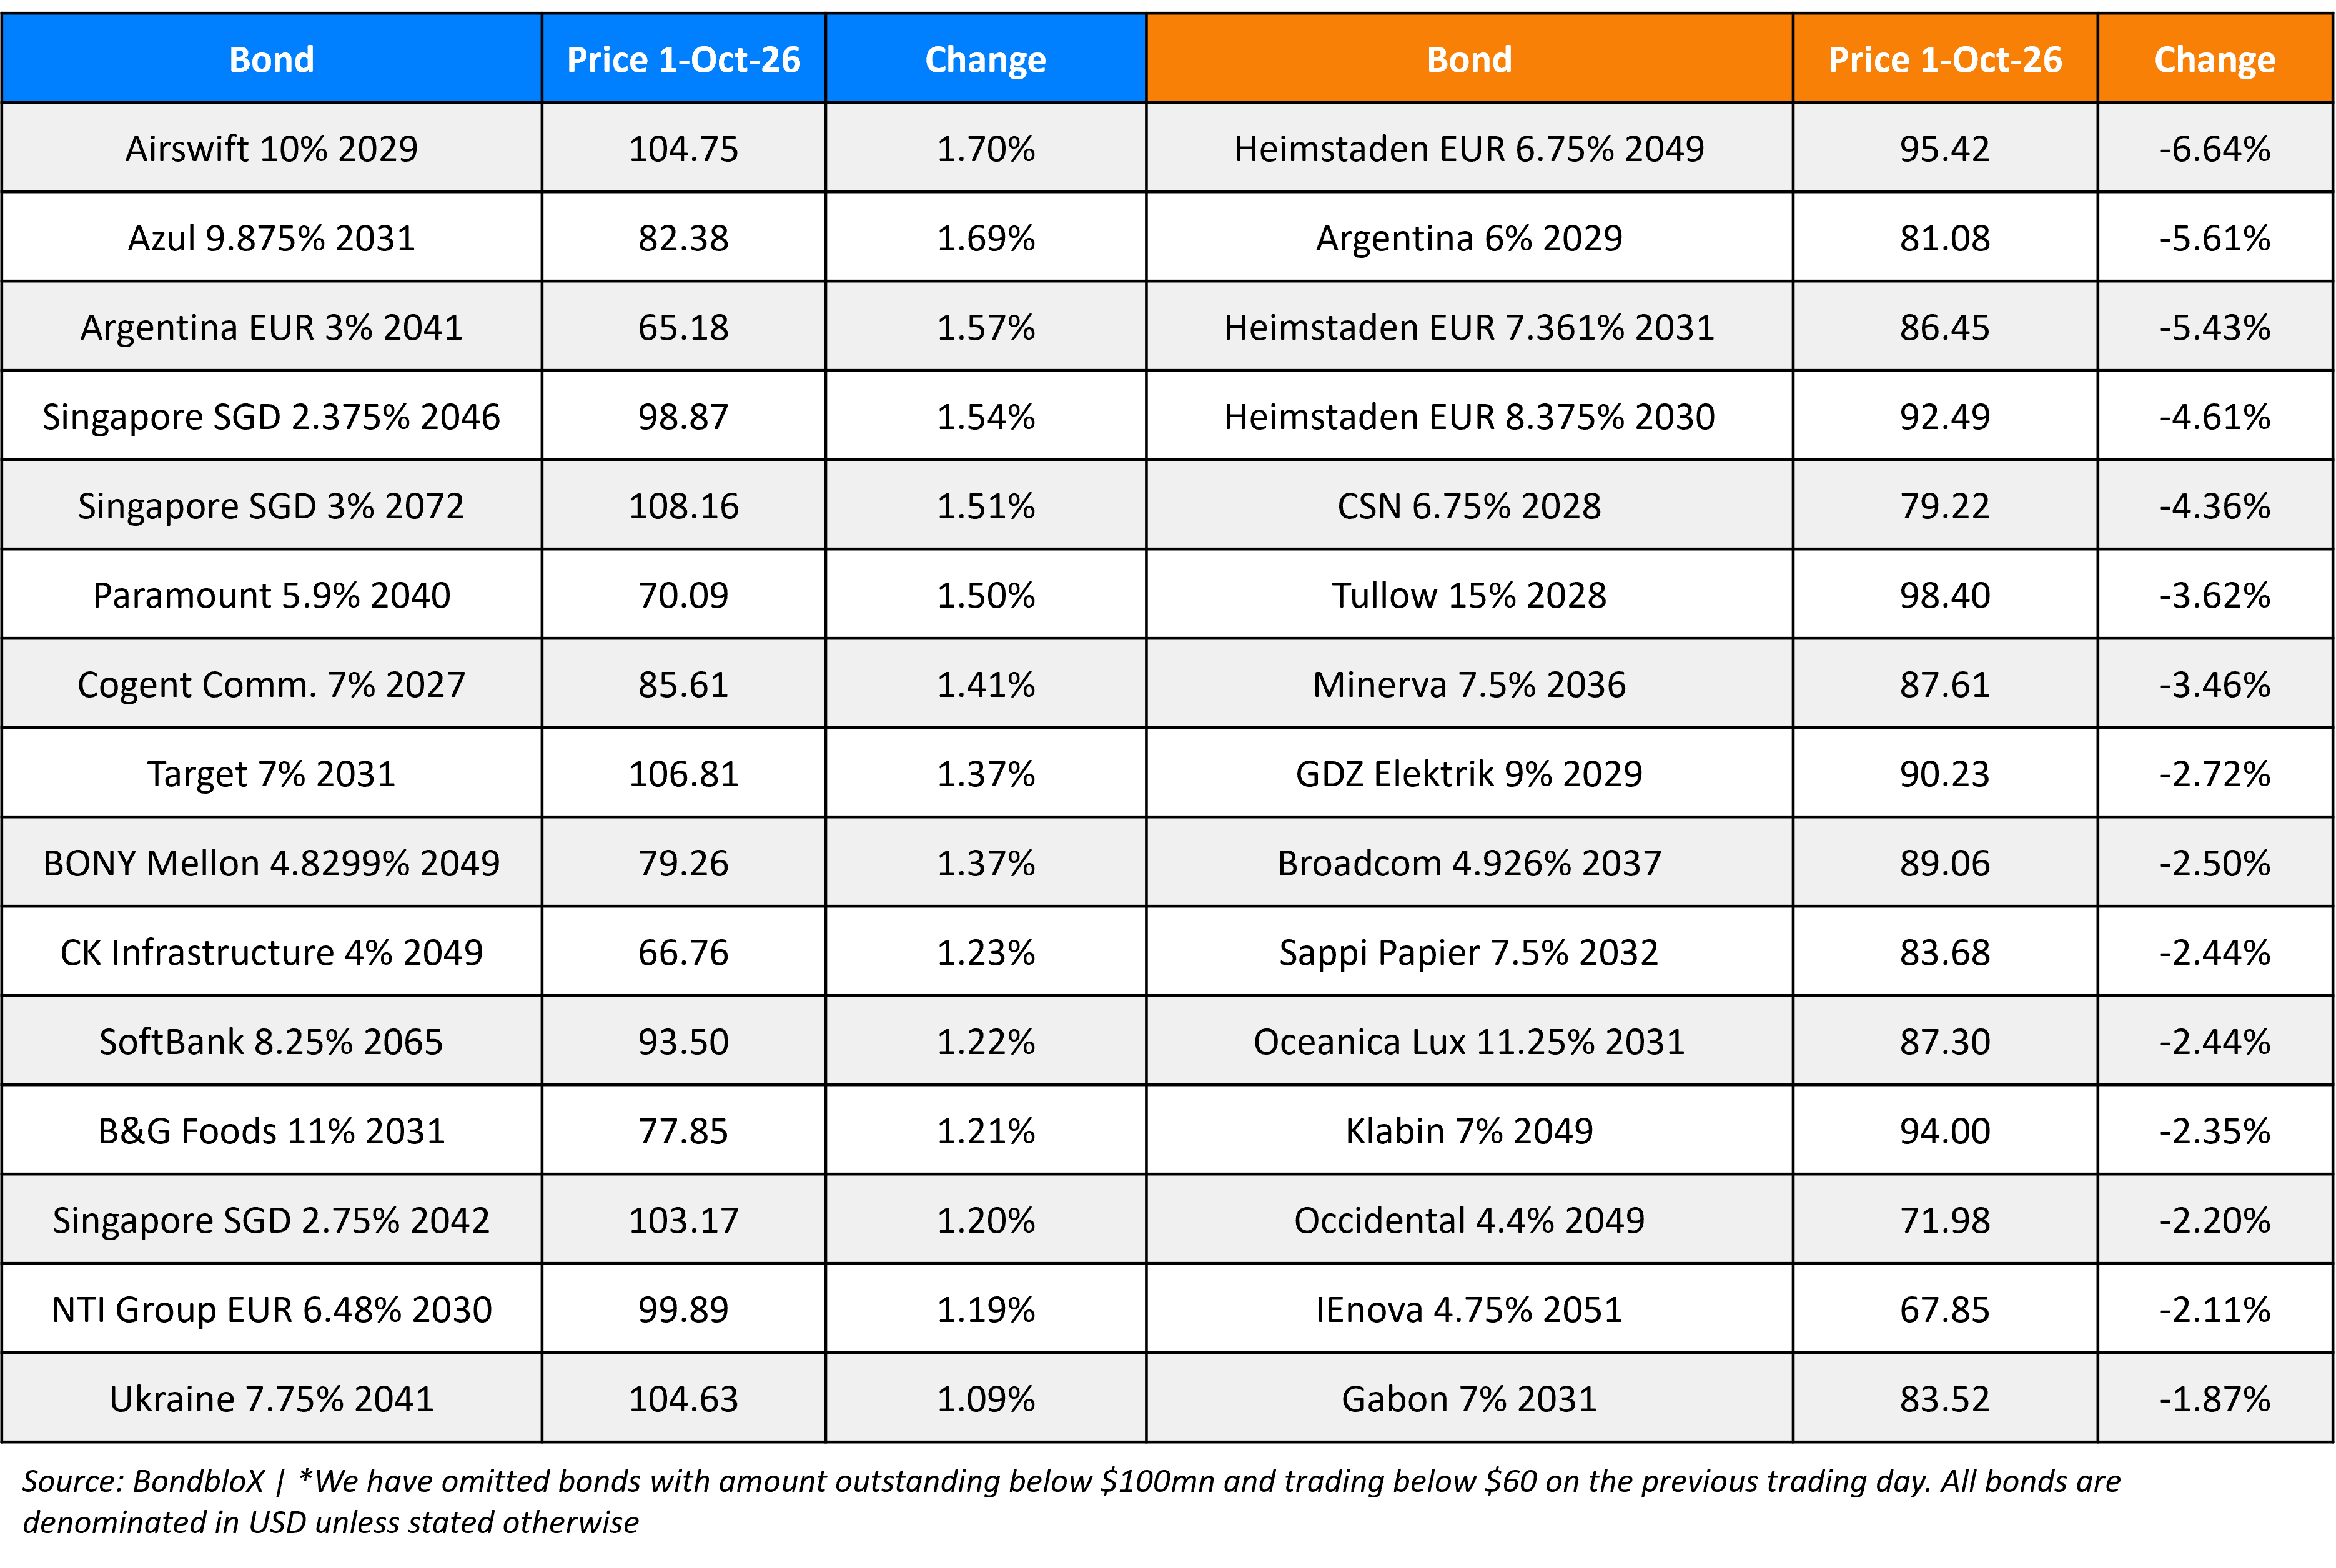
Top Gainers and Losers- 01-Oct-26*
Go back to Latest bond Market News
Related Posts: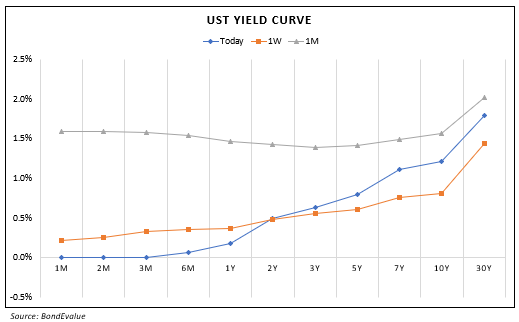
Our Awards
BondbloX Pte. Ltd. is regulated by the Monetary Authority of Singapore as a Recognised Market Operator ("RMO") and exempted from Section 49(1) of the Securities and Futures Act (Cap. 289) ("SFA") under Section 49(7) of the SFA.