We use cookies to improve your experience. By using BondbloX, you agree to our use of cookies.
Bond Market News
US Treasury yields rallied by 3-6bp across the curve
September 18, 2026

US Treasury yields rallied by 3-6bp across the curve. Brent crude declined for a third day as Saudi Arabia is working to restore around half the capacity of its cross-country oil pipeline within days after drone attacks forced a shutdown. Saudi Aramco plans to bypass the damaged section, with the pipeline expected to return to full capacity in about six weeks. In terms of data, Initial Jobless Claims for the week ending September 12, came in at 196k, lower than expectations of 207k and prior week’s print of 206k. UK yield curve bull flattened after the Bank of England kept its benchmark rate unchanged at 3.75% and paused Gilt sales. Meanwhile, the Bank of Japan raised its policy rate by 25bp to 1.25%, with the decision passing by a 7-2 vote.
Looking at equity markets, the S&P and the Nasdaq closed higher by 1.1% and 1.7% respectively. US IG CDS spreads were 1.6bp tighter, while HY CDS spreads tightened by 9bp. European equity markets also ended higher. European IG CDS spreads were 0.8bp tighter, and Crossover spreads tightened by 5.4bp. Asian equity markets have opened higher this morning. Asia ex-Japan CDS spreads tightened by 1.0bp.
Rating Changes
- Moody’s Ratings upgrades Cheplapharm’s rating to B2; outlook changed to positive
- Moody’s Ratings revised outlook on ReNew’s corporate family rating and ratings on five rated bonds to positive; Ratings affirmed
- Continuum Green Energy Ltd. ‘BB-‘ Rating Affirmed With Negative Outlook; SACP ‘bb-‘; Rating On Parent Withdrawn
- Fitch Revises ETESA’s Rating Outlook to Positive; Affirms at ‘B’
Term of the Day: Bull Flattening
Bull flattening refers to a change in the yield curve where long-term rates move down faster than short-term rates. This not only has a flattening effect on the entire yield curve but also has a net effect of interest rates moving lower and therefore bond prices moving higher, considered a bull move. On the other hand, the opposite move (interest rates move higher, bond prices move lower) is considered a bear move.
Talking Heads
“People love to use the phrase ‘higher for longer,… We would argue a far better characterization is normal for longer.”
“We see a case for a return to more ‘normal’ strategic bond allocations but the tactical case for adding long-dated bonds is mixed… We think bonds are increasingly becoming a tool for income generation but less for risk mitigation, similar to the 100 years before the late 1990s,”
On Weak Yen on BOJ Letdown – Chidu Narayanan, Wells Fargo
“The hurdle for the BOJ to meet these expectations is high, and even higher to exceed them,… The risk is skewed toward a more dovish-than-priced outcome.”
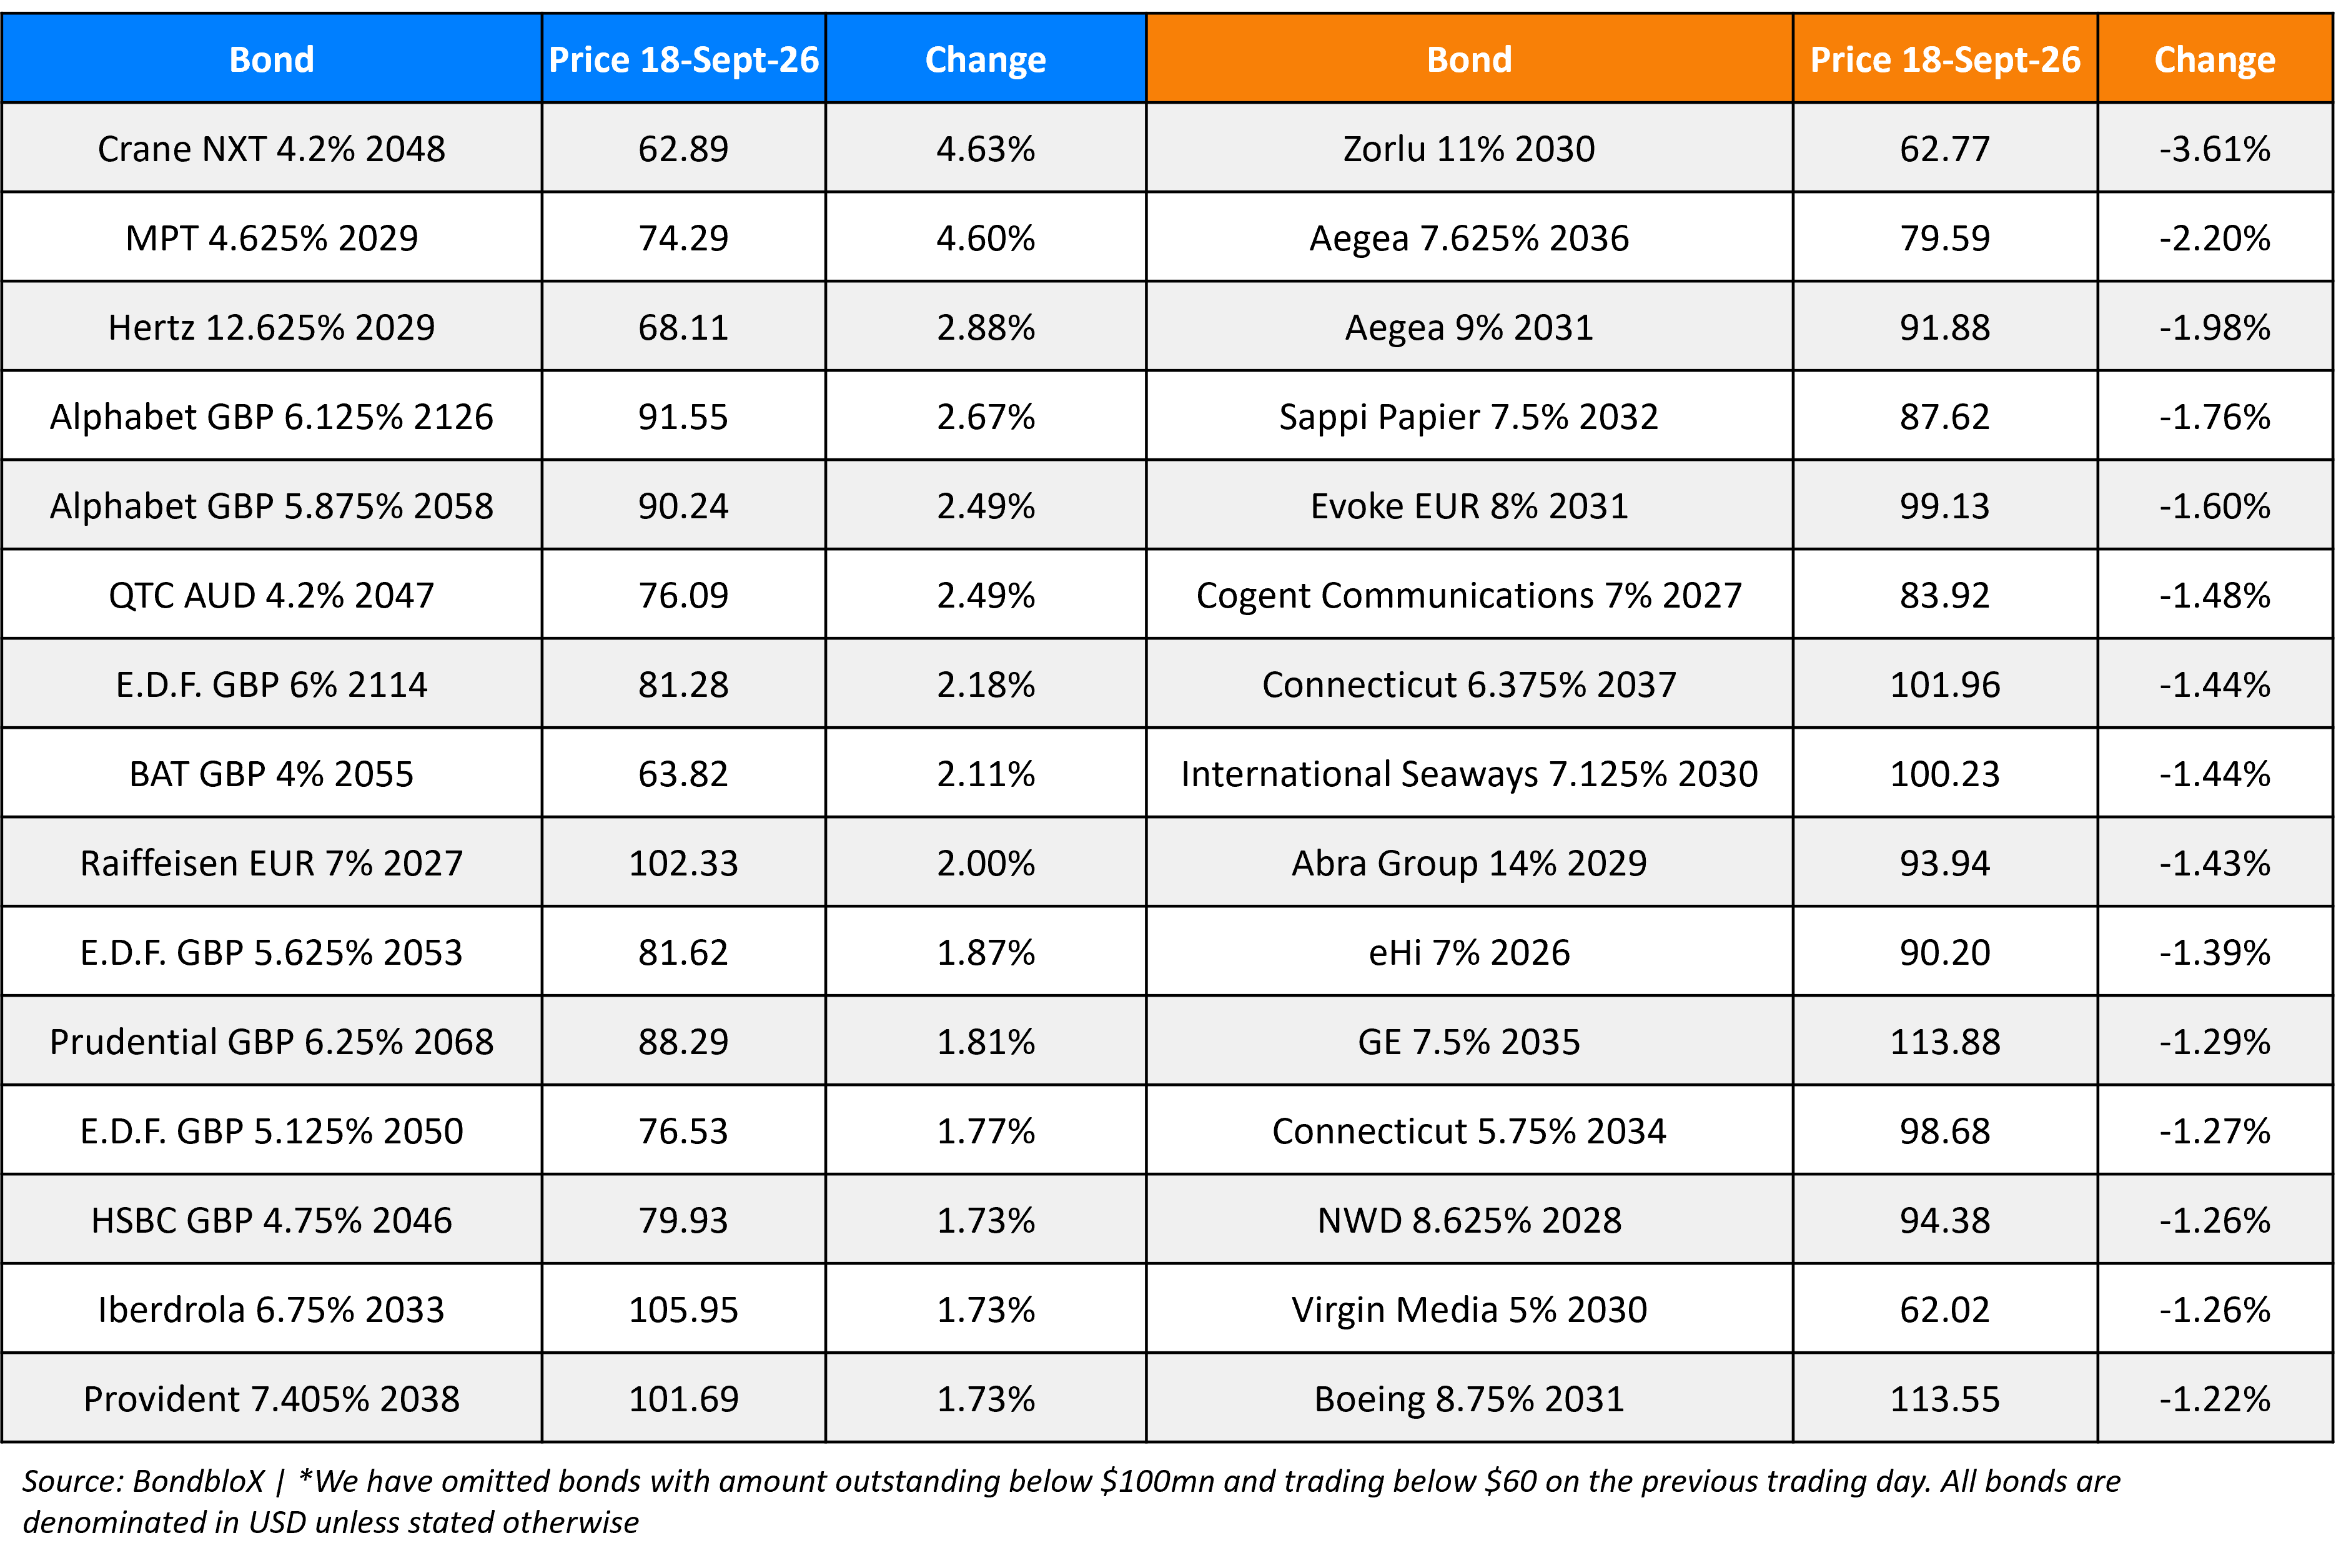
Top Gainers and Losers- 18-Sep-26*
Go back to Latest bond Market News
Related Posts: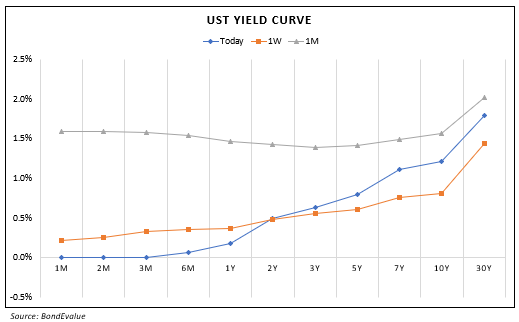
Our Awards
BondbloX Pte. Ltd. is regulated by the Monetary Authority of Singapore as a Recognised Market Operator ("RMO") and exempted from Section 49(1) of the Securities and Futures Act (Cap. 289) ("SFA") under Section 49(7) of the SFA.