We use cookies to improve your experience. By using BondbloX, you agree to our use of cookies.
Bond Market News
US Treasury Curve Bull Steepens
October 2, 2026

US Treasuries bull steepened with the short-end falling by 7-9bp, while 10Y fell by 3bp to close at 5.25%. On the data front, Initial Jobless Claims for last week came in at 197k, below expectations of 200k and in-line with the prior week’s print. The ISM Manufacturing PMI eased to 54.5 in September, vs expectations of 55.0 and prior month’s print of 54.6. Separately, Dallas Fed President Lorie Logan said further tightening is needed to cool inflation and estimates rates may need to rise by another 50bp or more. She added that higher Treasury term premiums could reduce the extent of additional Fed tightening required. Boston Fed President Susan Collins and Kansas City Fed President Jeff Schmid said inflation remains too high, with both indicating that further tightening may be needed to bring inflation sustainably back to 2%. Meanwhile, Fed Vice Chair Philip Jefferson and Vice Chair for Supervision Michelle Bowman signaled a more patient approach, suggesting Fed should take more time before deciding on further rate hikes.
Looking at equity markets, the S&P closed higher by 0.2% while Nasdaq ended flat. US IG CDS spreads were 0.3bp wider, while HY CDS spreads widened by 3.4bp. European equity markets ended lower. European IG CDS spreads were 2.8bp wider, and Crossover spreads were 13.6bp wider. Asian equity markets have opened broadly mixed this morning. Asia ex-Japan CDS spreads widened by 0.1bp.
New Bond Issue
DNB Bank raised $750mn via a 6NC5 bond at a yield of 5.904%, 22.5bp inside initial guidance of T+112.5bp area. The senior non-preferred note is rated A2/A. Proceeds will be used for general corporate purposes.
Rating Changes
- Fitch Upgrades Bank of Ceylon’s IDRs to ‘B-‘, VR to ‘b-‘; Outlook Stable
- Herens Midco S.a.r.l. Upgraded To ‘B-‘ On Implementation Of Debt Amendment; Outlook Negative
- Moody’s Ratings downgrades Vestel to Ca; outlook negative
- Fitch Revises Sappi’s Outlook to Negative; Affirms IDR at ‘BB’
Term of the Day: PMI
PMIs or Purchasing Managers’ Index are an index composed of a monthly survey of purchasing managers/supply chain managers across industries. This is a diffusion index, a statistical measure of summarizing the common tendency of a series – if there are more number of values rising than falling, the index is above 50 and the index goes below 50 if the falling values exceed those rising. For PMIs, a value below 50 indicates contraction and a value above 50 shows expansion. These surveys are taken over different areas of the supply chain business: New Orders, Employment, Inventories, Supplier Deliveries and Production covering imports, exports, prices and backlogs. In most countries, Markit publishes the PMI numbers while other organizations publish them too. Markit generally publishes the month’s PMIs in last week of the month.
Talking Heads
“There’s a deep short base in the market and no surprise there are a lot of shorts in the 10-year,… The WI announcement and the auction will bring more shorts into the issue. I expect the 10-year will continue to be volatile for the next two weeks.”
On Australia-US Bond Yield Gap Nears Zero as Policy Paths Diverge – Kenneth Crompton, NAB
“Whilst our base case is 10-year Australia-US Treasury spread inversion to happen during 2027, it wouldn’t be out of line for it to happen now,… By the end of next year if RBA and Fed expectations diverge as much as we expect, then the spread can easily re-test the -20 basis point level.”
On Europe’s Bond Spreads Spike as French Debt Risk Spills Over
Mike Riddell, Fidelity International
“France has been slowly but steadily breaking,… But today feels like the first day that broader financial markets have noticed.”
Rohan Khanna, Barclays
“The price action is very unusual,… We are reducing ECB rate hike expectations, yet the EGB complex, with the exception of Germany and the Netherlands, is selling off. It is reminiscent of periods when bond market fragmentation was a major concern, such as during the European sovereign debt crisis.”
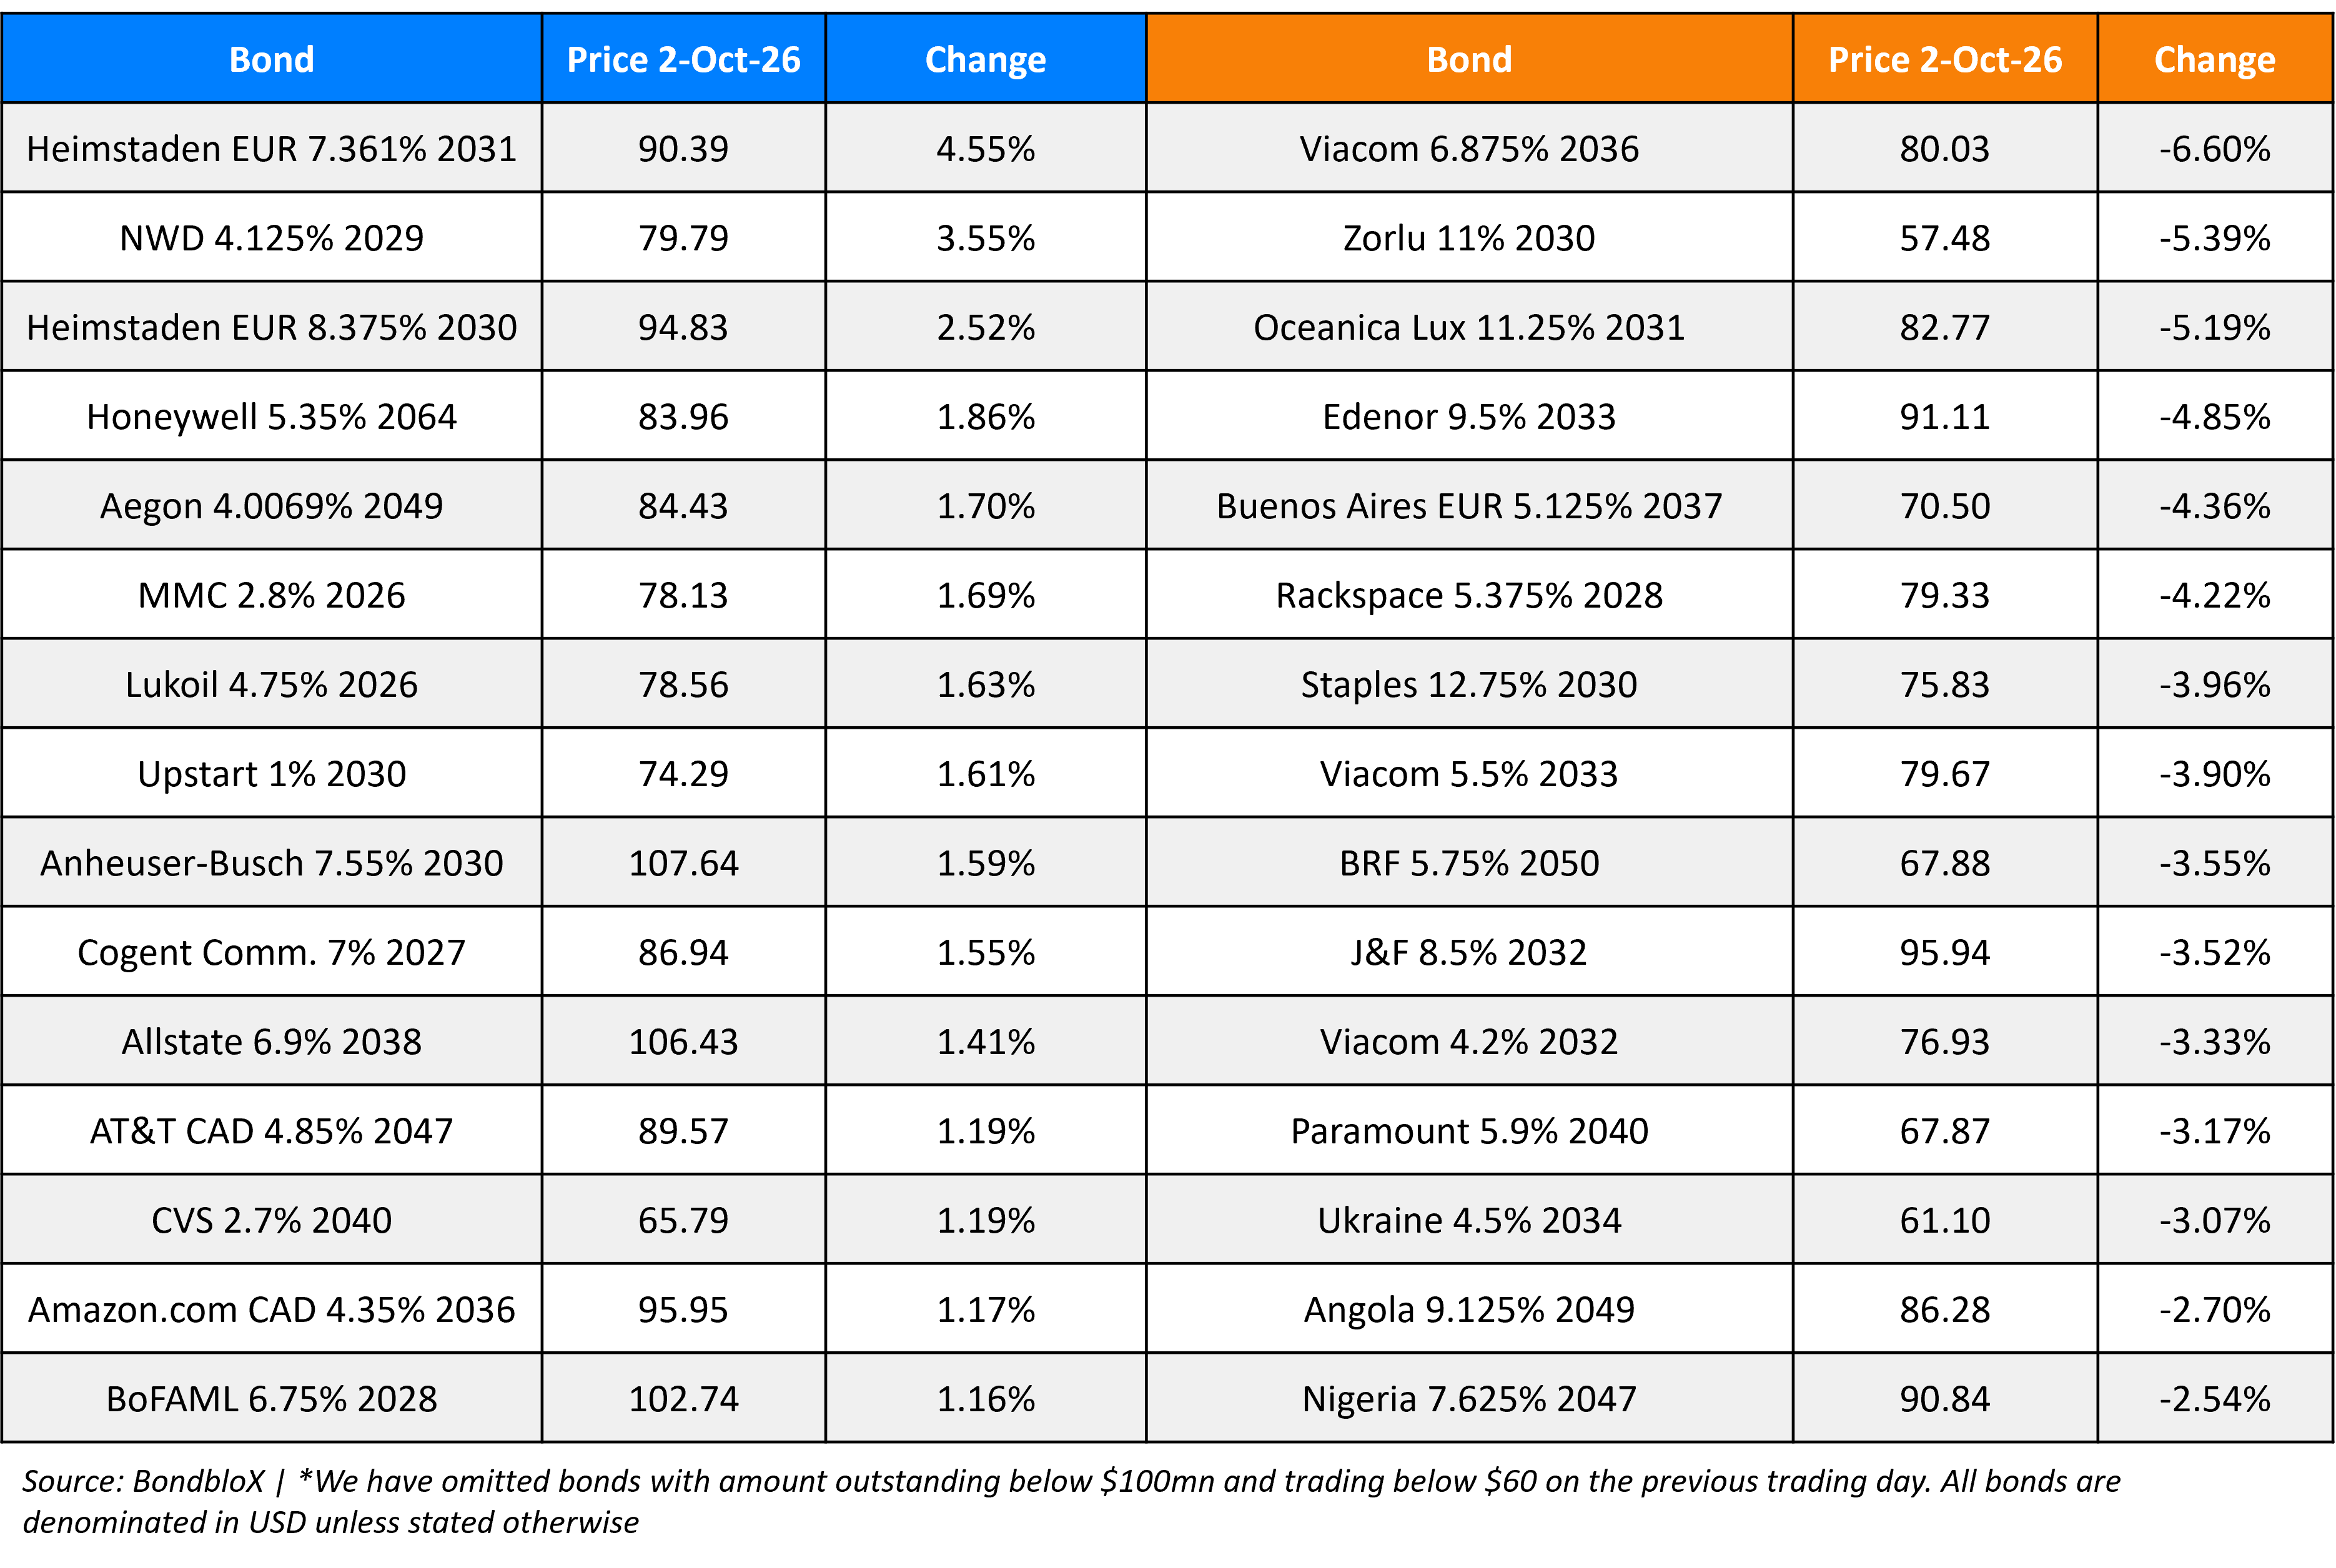
Top Gainers and Losers- 02-Oct-26*
Go back to Latest bond Market News
Related Posts: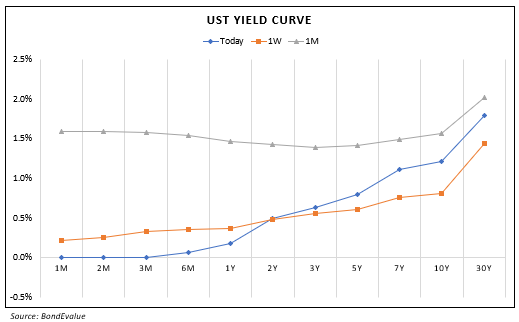
Our Awards
BondbloX Pte. Ltd. is regulated by the Monetary Authority of Singapore as a Recognised Market Operator ("RMO") and exempted from Section 49(1) of the Securities and Futures Act (Cap. 289) ("SFA") under Section 49(7) of the SFA.