We use cookies to improve your experience. By using BondbloX, you agree to our use of cookies.
Bond Market News
The US Treasury yield curve bear-flattened
October 12, 2026

The US Treasury yield curve bear-flattened with the short-end yields rising by 3-4bp while the long-end yields held broadly steady. On the data front, the preliminary reading of the University of Michigan Consumer Sentiment Index for October fell to 46.3, below expectations of 47.6 and September’s reading of 48.1. Markets now await CPI data this week for further cues on the Fed’s rate path. Separately, President Donald Trump announced that Russian President Vladimir Putin had agreed to release 300k tonnes of diesel immediately into the US and global markets, with further shipments expected. The announcement came just weeks after the US authorised fresh sanctions and tariffs on countries importing Russian oil and gas. Separately, Saudi Arabia’s main airport faced renewed attacks from Houthi rebels on Sunday, following a strike on previous day that killed 12 people.
Looking at equity markets, both the S&P and the Nasdaq closed higher by 0.6% each. US IG CDS spreads tightened by 0.8bp, while HY CDS spreads tightened by 4.5bp. European equity markets also ended higher. European IG CDS spreads were 0.5bp tighter, and Crossover spreads were 7.1bp tighter. Asian equity markets have opened broadly mixed this morning. Asia ex-Japan CDS spreads tightened by 1.3bp.
PepsiCo raised €1bn via a two-part deal. It raised €500mn via a 3Y bond at a yield of 3.767%, 27bp inside initial guidance of MS+60bp area. It also raised €500mn via a 9Y bond at a yield of 4.274%, 32bp inside initial guidance of MS+105bp area. The senior unsecured notes are rated A1/A+. Proceeds will be used for general corporate purposes.
New Bonds Pipeline
- PT Bank KB Indonesia $ 3Y bond
- HB CGIF G’TEED S$ 3Y/5Y Social bond
Rating Changes
- Moody’s Ratings upgrades Ghana’s ratings to B3, changes outlook to stable
- Moody’s Ratings upgrades TIM’s ratings to Baa3; positive outlook
- United Rentals Inc. Upgraded To ‘BBB-‘ From ‘BB+’ On Disciplined Financial Policy And Lower Leverage; Outlook Stable
- Fitch Revises Nigeria’s Outlook to Positive; Affirms at ‘B’
- Moody’s Ratings revises Crescent Energy’s outlook to positive; affirms Ba3 CFR
Term of the Day: Defeasance
Defeasance is a financial strategy where a borrower nullifies debt by allocating adequate cash or bonds, removing it from the balance sheet. This process not only mitigates prepayment penalties but also maintains the flow of interest payments to bondholders.
Talking Heads
On Bessent Will Likely Cut US Long Bond Sales Next Month – Citibank
“(It is likely that there will be a) reduction, or perhaps cancellation, of the 20-year bond…. While we do not think such IG supply has impacted the overall level of rates, we do think pension funds could be leaning into long-end IG bonds more than they typically have.”
On A Higher-Rate World Is in Store as Central Banks Approach 2027 – Tom Orlik, Bloomberg
“The Iran war is an up arrow for inflation — and has already forced central banks into action. A multi-decade high for bond yields is a down arrow. Tighter financial conditions don’t get central banks off the hook for controlling price pressure. They do temper expectations on how many hikes are ahead.”
“Compared to 2011, EMs are better positioned today, with stronger fiscal dynamics, external balances, and high nominal yields that provide structural resilience,”
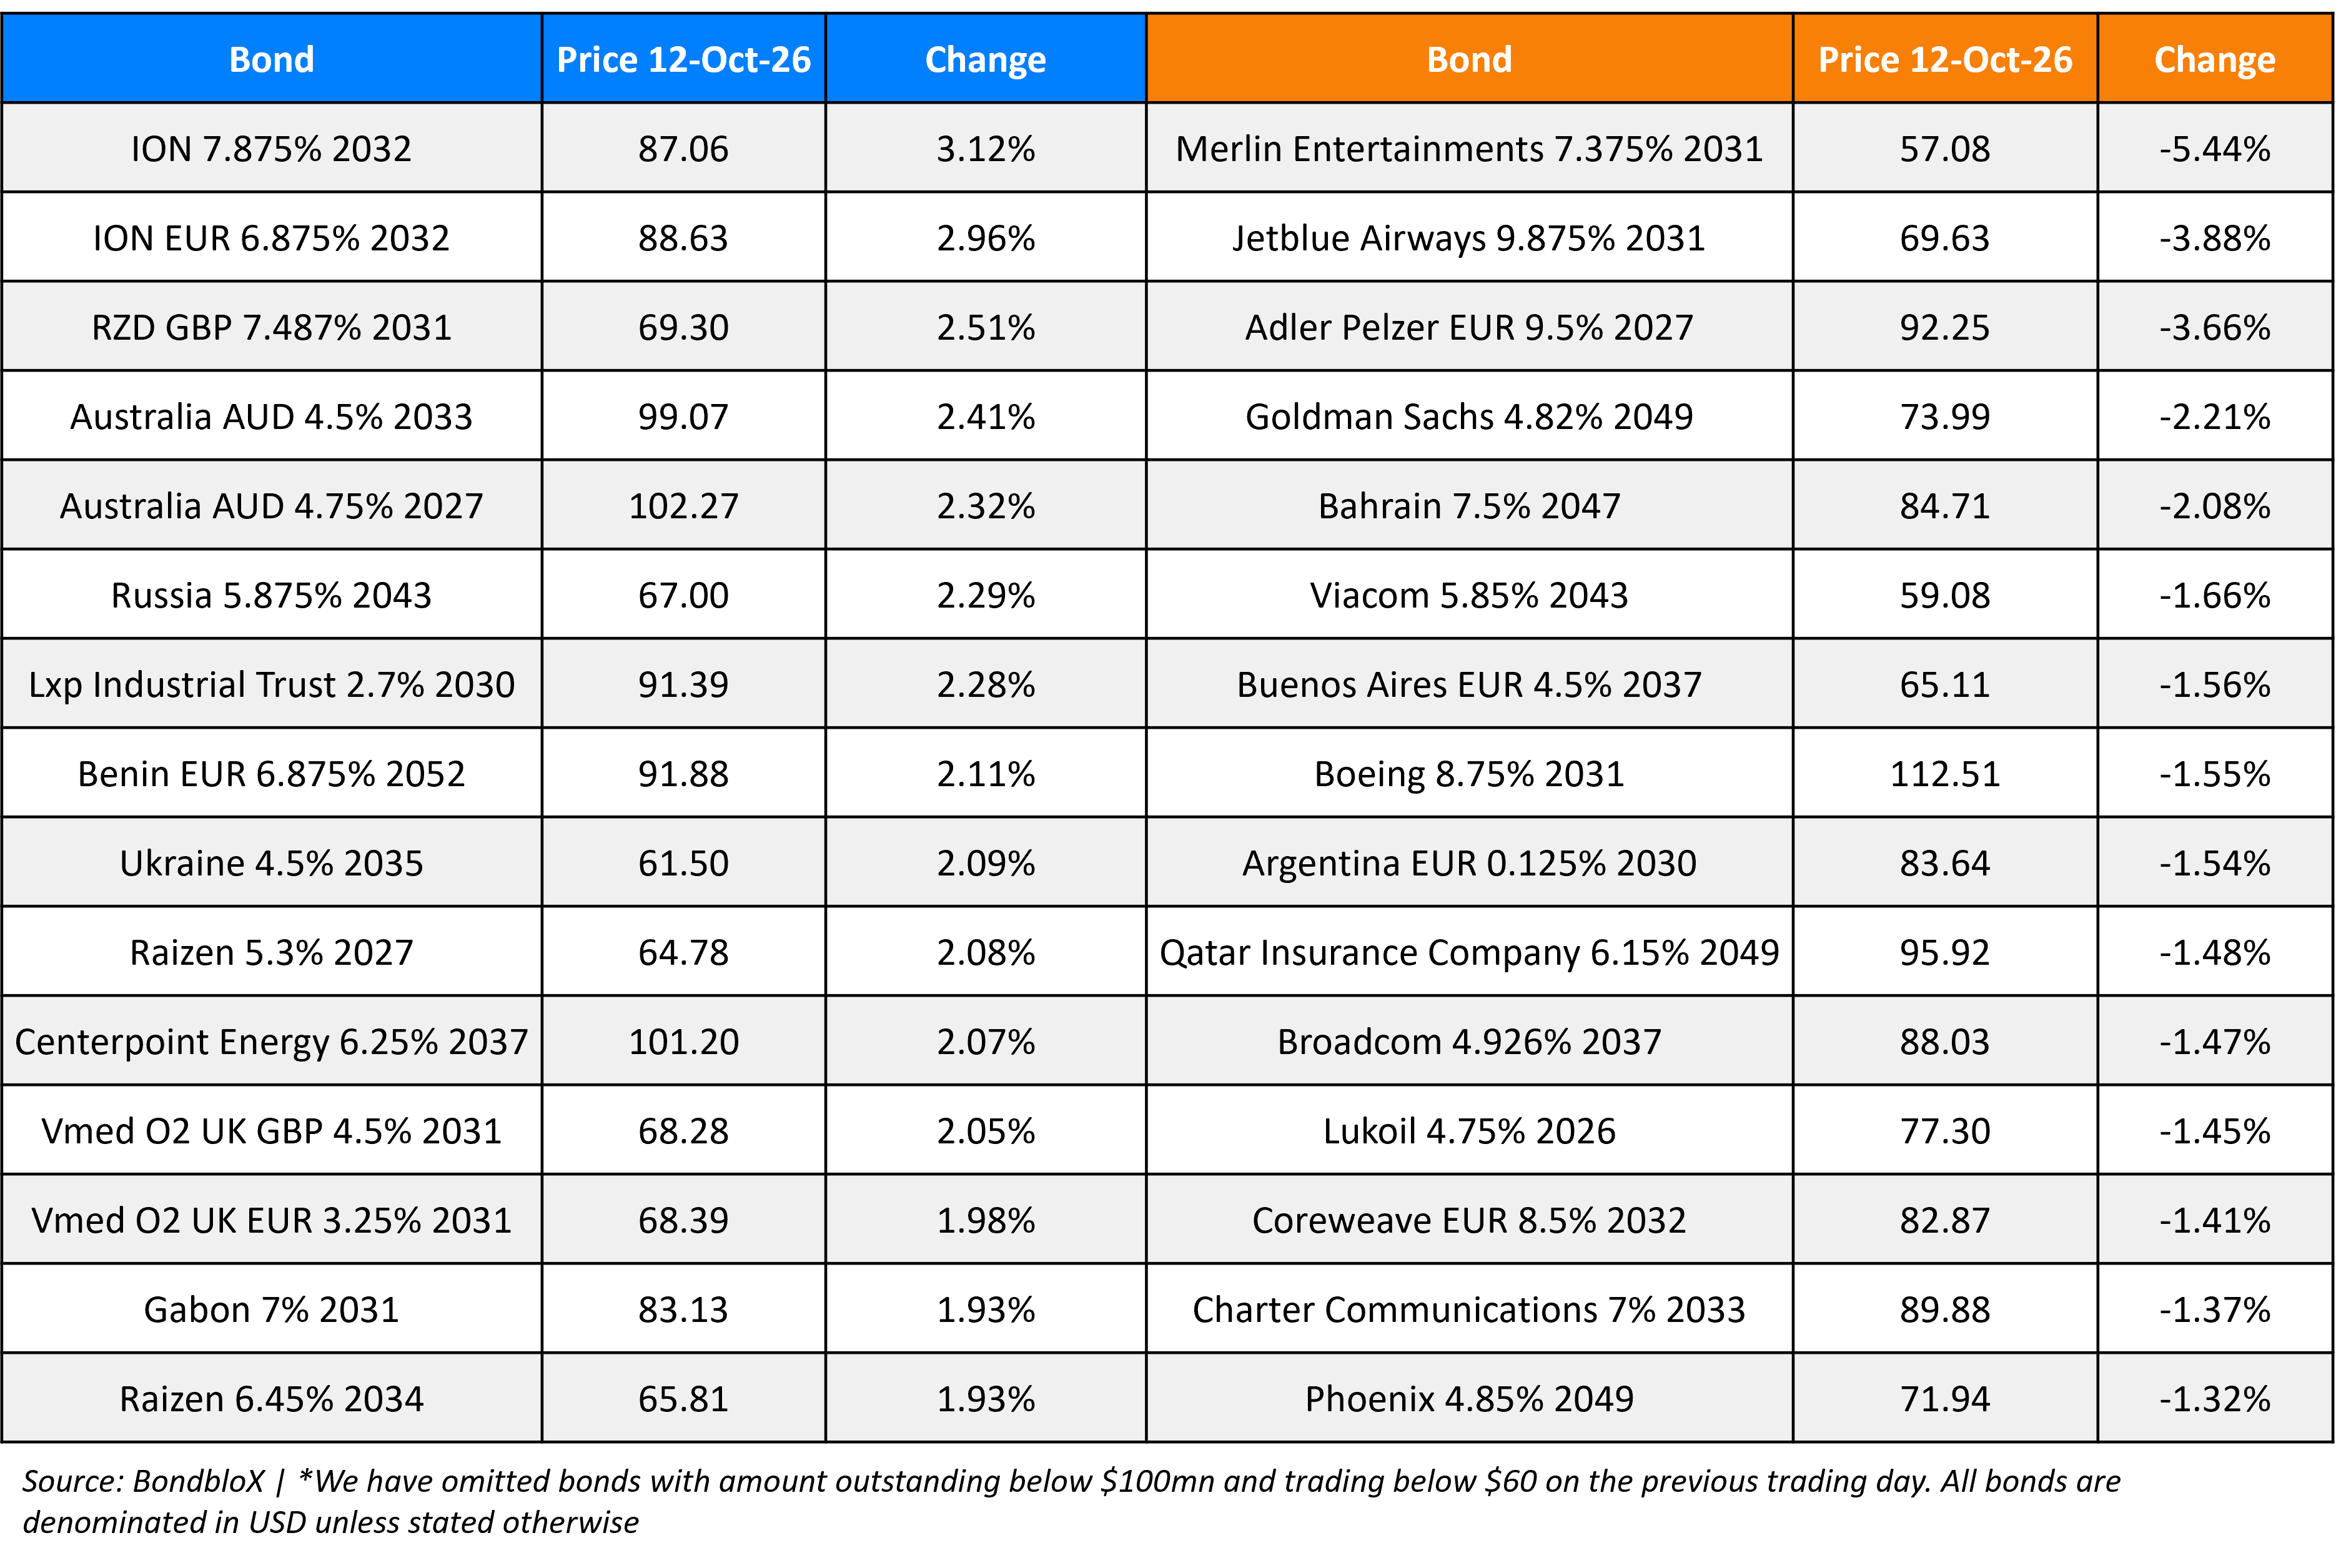
Top Gainers and Losers- 12-Oct-26*
Go back to Latest bond Market News
Related Posts: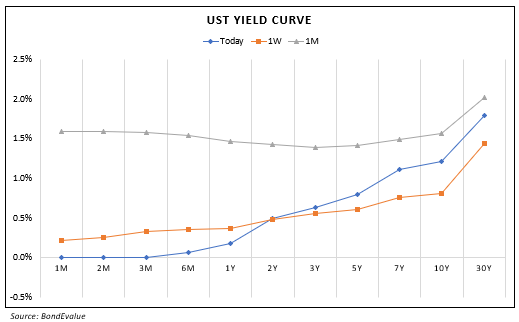
Our Awards
BondbloX Pte. Ltd. is regulated by the Monetary Authority of Singapore as a Recognised Market Operator ("RMO") and exempted from Section 49(1) of the Securities and Futures Act (Cap. 289) ("SFA") under Section 49(7) of the SFA.