We use cookies to improve your experience. By using BondbloX, you agree to our use of cookies.
Bond Market News
Tencent, Dah Sing Bank, and Others Launch Bonds
October 13, 2026

US Treasury yields eased by 2-5bp across the curve. Cleveland Fed President Beth Hammack favoured a gradual approach to monetary tightening, arguing that frequent adjustments could help contain inflation expectations. She refrained from signaling support for an October rate hike, noting that officials still have more data to assess ahead of the upcoming meeting. Hammack also highlighted the importance of clear communication while avoiding firm guidance on future interest rates. Markets now await US CPI data tomorrow for further cues on inflation and the Fed’s rate path.
Looking at equity markets, the S&P and the Nasdaq closed lower by 0.1% and 0.4% respectively. US CDS markets were closed on account of the Columbus Day holiday. European equity markets ended higher. European IG CDS spreads widened by 0.2bp, and Crossover spreads were 2.3bp wider. Asian equity markets have opened broadly lower this morning. Asia ex-Japan CDS spreads tightened by 0.4bp.
New Bond Issues
- Tencent $ 10Y/20Y at T+115bp/T+140bp areas
- Dah Sing Bank $10.5NC5.5 Tier-2 at T+165bp area
- KEB Hana Bank $ 3Y/5Y at T+75bp/T+80bp areas
- Hanwha Energy USA $ 3Y at T+90bp area
- Emirates Islamic Bank $ 5Y sukuk at T+145bp area
Ausnet raised €620mn via a 10.5Y bond at a yield of 4.744%, 33bp inside initial guidance of MS+150bp area. The senior unsecured notes are rated Baa1/BBB+. Proceeds will be used to repay existing debt and for general corporate purposes.
New Bonds Pipeline
- Julius Baer Group S$ PerpNC5 AT1
- Samsung Life Insurance $ 30NC5 Tier-2 notes
- PT Bank KB Indonesia $ 3Y bond
- HB CGIF G’TEED S$ 3Y/5Y Social bond
Rating Changes
- DISH DBS Corp. Upgraded To ‘CCC+’ On Emergence From Bankruptcy; On CreditWatch Positive
- Sandisk Corp. Upgraded To ‘BBB’ From ‘BB+’ On Demand Upsurge; Outlook Stable
- Warner Bros. Discovery Inc. Downgraded To ‘BB’ On Completion Of Acquisition By Skydance Corp., Outlook Stable
- Macy’s Inc. Outlook Revised To Positive On Operational Improvements; Ratings Affirmed
Term of the Day: Duration
Duration or Macaulay Duration for a fixed income security is the weighted average time until repayment of the invested amount. Duration is measured in years and for coupon-bearing vanilla fixed-rate bonds, duration is less than the tenor of the bond. The higher the duration, the higher will be the change in a bond’s price for a given change in interest rates. Given duration’s weightage to coupon payments, it is a more accurate measure of interest rate risk vs. the tenor of the bond. The higher the bond’s coupon, lower will be its duration and; the higher the tenor, greater will be the bond’s duration, all else equal. For very long tenor bonds like century (100Y) bonds or very high coupon bonds, the duration is significantly less than the tenor. On the other hand, zero coupon bonds’ duration are equal to its tenor.
Talking Heads
On Wall Street Revives the Case for Scrapping the US 20-Year Bond
Padhraic Garvey, ING Groep NV
“If you wanted to do something, leave everything and cut the 20 year,… Nobody likes the 20 years. But our baseline view is he leaves it as it is.”
Jason Williams, Citigroup
“Bessent may point to poor pension-fund Treasury demand, perhaps caused by increased long-end corporate bond issuance, as a reason to reduce and/or cancel the 20y bond”
On Surging Bond Yields Are Top Risk to Financial System – IMF
“High debt and rollover risks remain unresolved, making the bond market susceptible to more frequent fiscal and inflation shocks”
On Turning Bullish on Short-Term Bonds, Downgrades Stocks – Blackrock
“Now, yields have reset toward our long-held higher-rates view, and we want to lock in some attractive income”
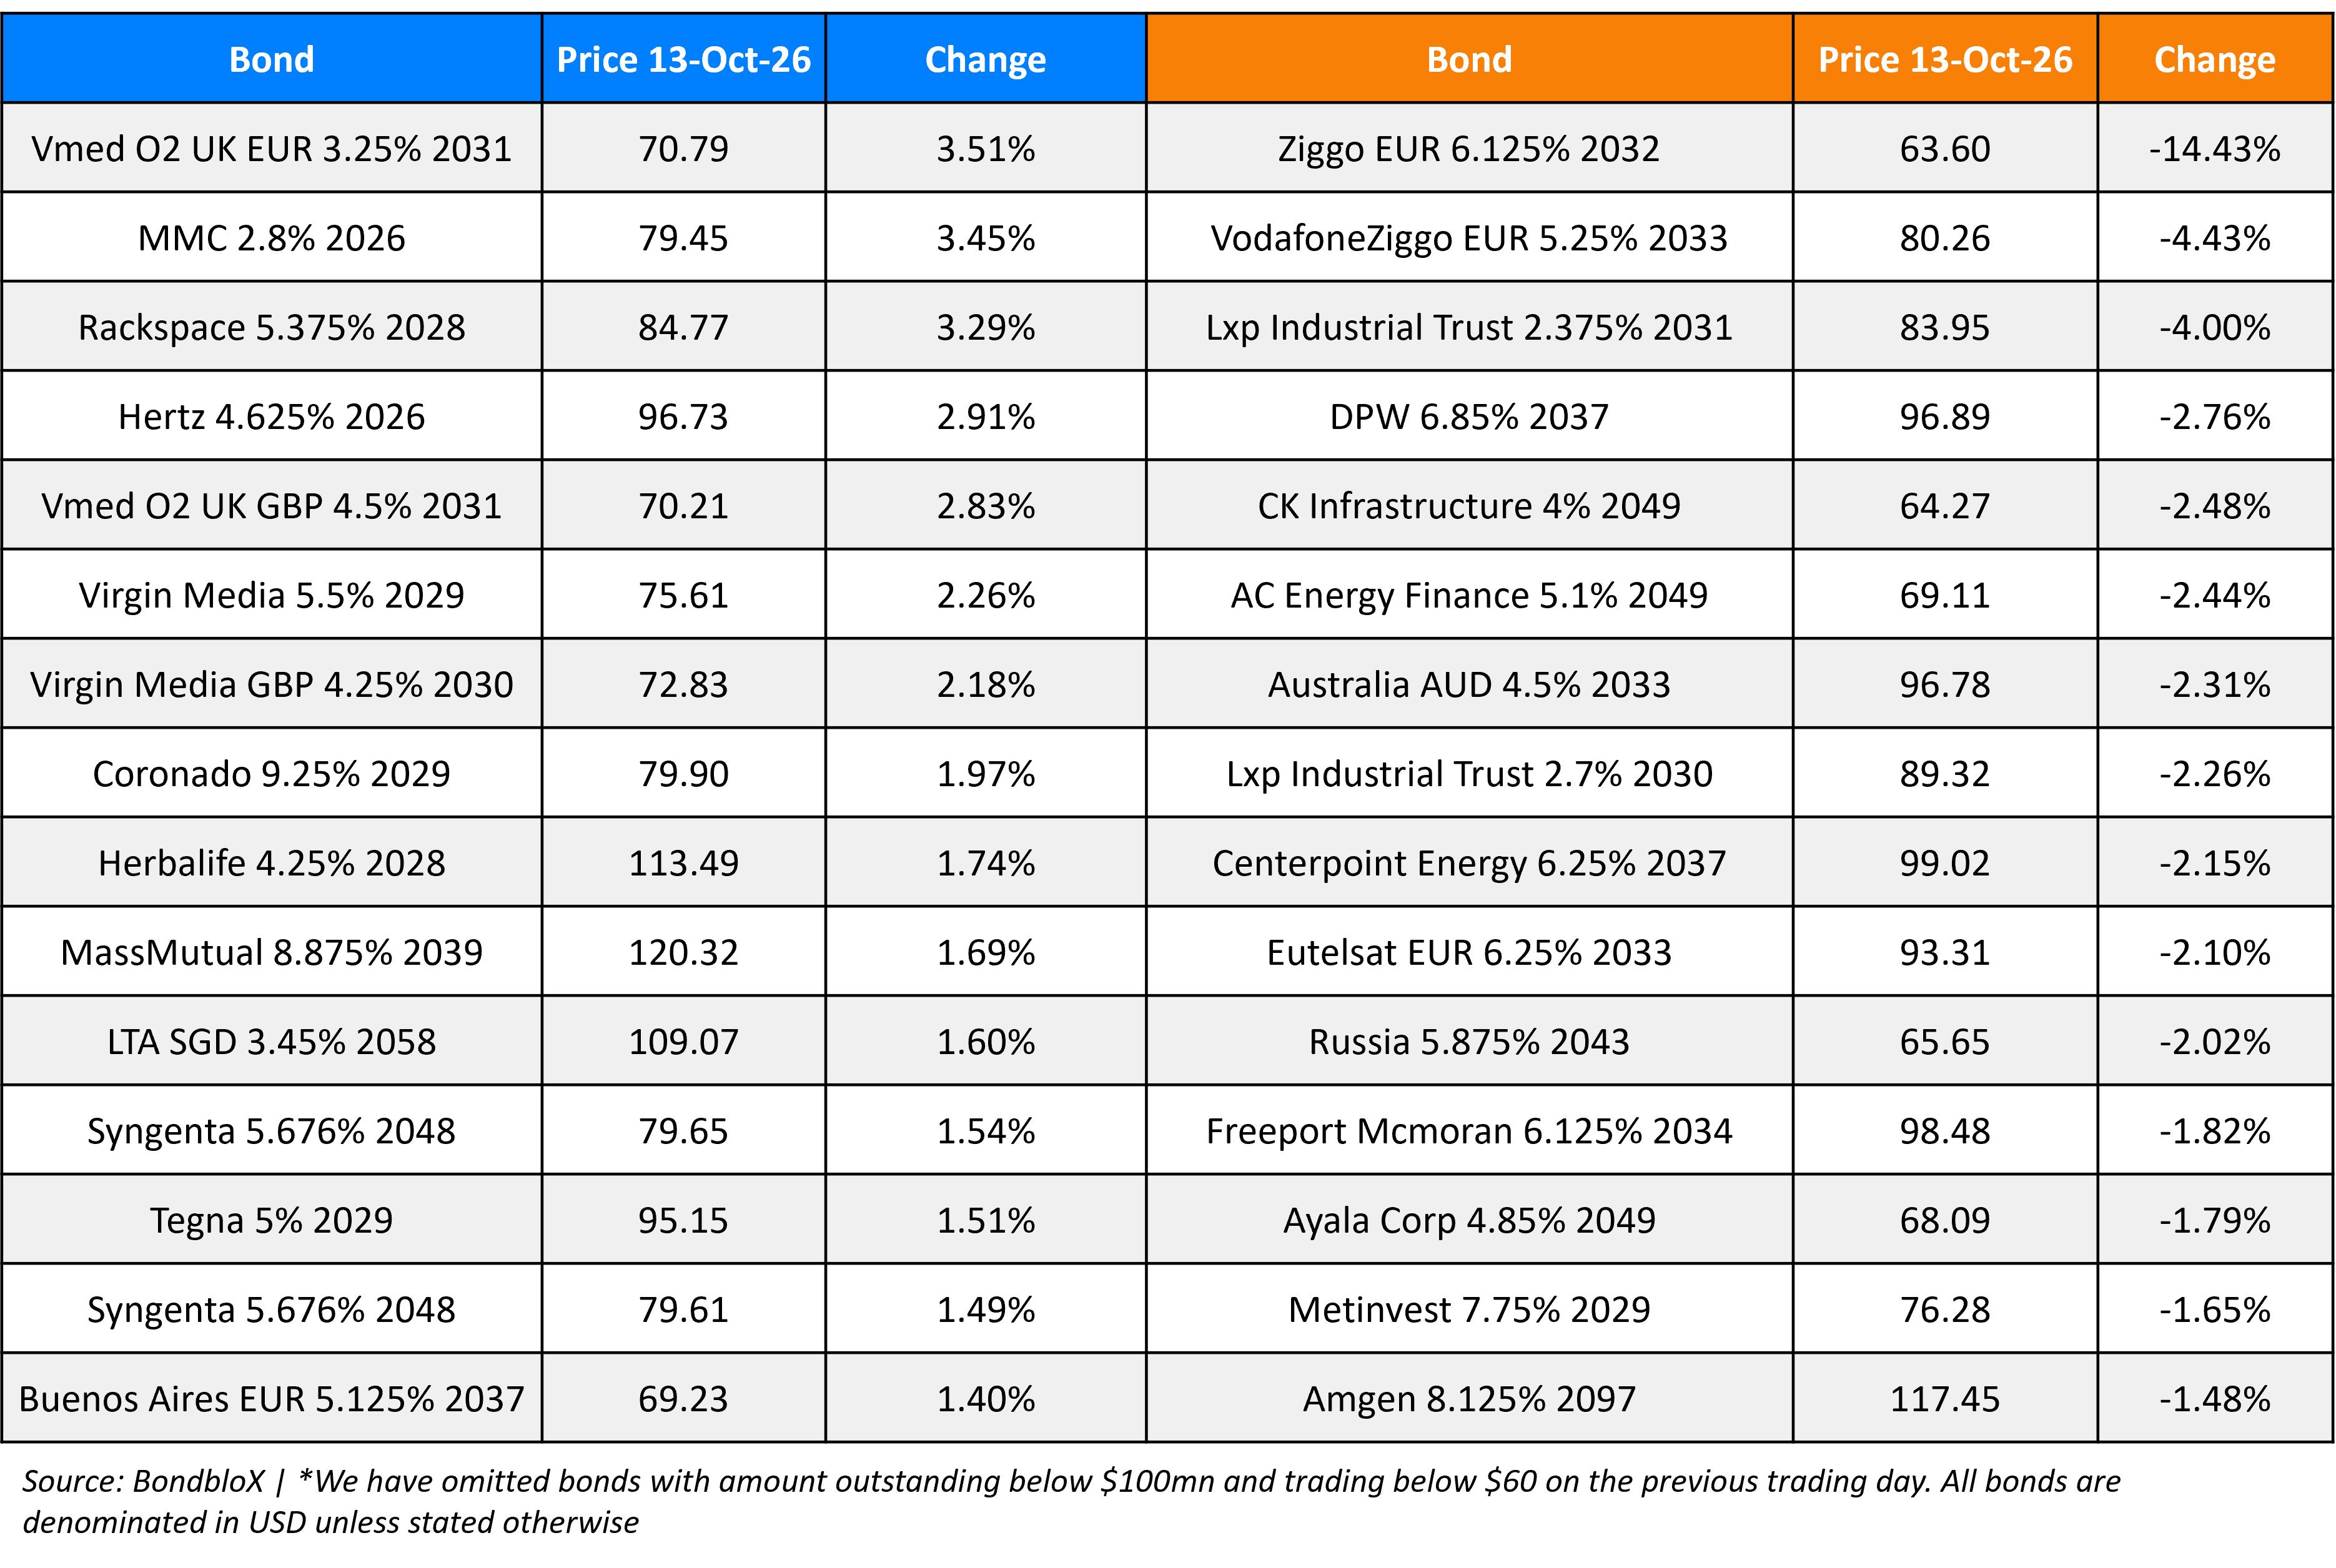
Top Gainers and Losers- 13-Oct-26*
Go back to Latest bond Market News
Related Posts: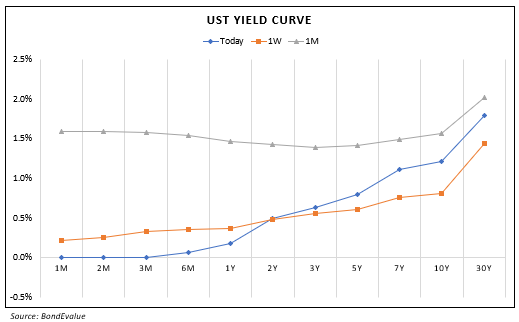
Our Awards
BondbloX Pte. Ltd. is regulated by the Monetary Authority of Singapore as a Recognised Market Operator ("RMO") and exempted from Section 49(1) of the Securities and Futures Act (Cap. 289) ("SFA") under Section 49(7) of the SFA.