We use cookies to improve your experience. By using BondbloX, you agree to our use of cookies.
Bond Market News
NFP Softens, Markets Price-in 25bp Hike in December
October 5, 2026

US Treasury yields were broadly stable across the curve except 30Y which eased by 3bp to 5.6%. The 2Y was at 4.8% while the 10Y was at 5.25% On the data front, US Nonfarm Payrolls rose by just 29k in September, softer than expectations of 90k, and prior month’s revised print of 133k. Average Hourly Earnings growth eased to 3.0% YoY, below expectations of 3.1%, while the Unemployment rate rose to 4.2% against expectations of 4.1%. Following the data, markets scaled back expectations for further Fed tightening in October. Separately, Treasury Secretary Scott Bessent said the recent rise in US Treasury yields was broadly in line with global moves and did not warrant concern. He also highlighted underlying strength in the US economy, pointing to strong consumer spending and median wage growth despite the impact of the Iran war.
Looking at equity markets, the S&P and the Nasdaq closed higher by 0.7% and 1.2% respectively with Nasdaq reaching an all-time intraday high on Friday. US IG CDS spreads widened by 0.1bp, while HY CDS spreads widened by 0.5bp. European equity markets also ended higher. European IG CDS spreads were 1.0bp tighter, and Crossover spreads were 3.8bp tighter. Asian equity markets have opened broadly higher this morning. Asia ex-Japan CDS spreads widened by 2.9bp.
Rating Changes
- Fitch Upgrades LATAM Airlines’ IDRs to ‘BB+’; Outlook Stable
- Moody’s Ratings downgrades Edgewell’s CFR to B1; outlook stable
- Fitch Revises Outlook on Sun Hung Kai Properties to Positive; Affirms Rating at ‘A’
- Romania ‘BBB-/A-3’ Ratings Affirmed; Outlook Negative
- Fitch Affirms Ras Al Khaimah at ‘A+’; Removes from Rating Watch Negative; Outlook Negative
Term of the Day: Credit Default Swap (CDS)
A Credit Default Swap (CDS) is a financial contract between two counterparties that allows an investor to “swap” or offset the credit risk with another investor. CDS acts like an insurance policy wherein the buyer makes regular payments to the seller to protect itself from an issuer default. In the event of a default, the buyer receives a payout, typically the face value of the bond or loan, from the seller of the CDS as per the agreement. CDS spreads are a commonly used metric to track the market-priced creditworthiness of an issuer. A widening (increase) in CDS spreads indicates a deterioration in creditworthiness and vice-versa.
Talking Heads
On Wall Street Strategists Steer Investors to Cross-Asset Hedges – Neeraj Chaudhary, Bank of America
“We’ve recently seen a tendency to fade the move in rates, with positioning for yields to move lower,… In US equities, flows have been predominantly bullish, while in Europe the bias has been more bearish.”
On Wall Street’s AI Party Is on Edge as Soaring Yields Raise Risks – Robert Schiffman, Bloomberg
“These companies (Hyperscalers) initially entered this AI build phase with maximum flexibility, holding pristine AA and AAA credit profiles, what we call the Mount Rushmore of corporate credits,… Today, however, hyperscalers like Meta, Amazon, Alphabet, Microsoft and Oracle have cash needs that far exceed internal cash sources, forcing a turn to debt markets that will drive leverage up over the next two years.”
On Whispers of Contagion Risk Are Returning to Europe’s Bond Market – Jeff Mueller, Morgan Stanley
“We are starting to see first signs of contagion,… If the erratic price action observed on Oct. 1 continues for some time, this may draw some attention from policymakers.”
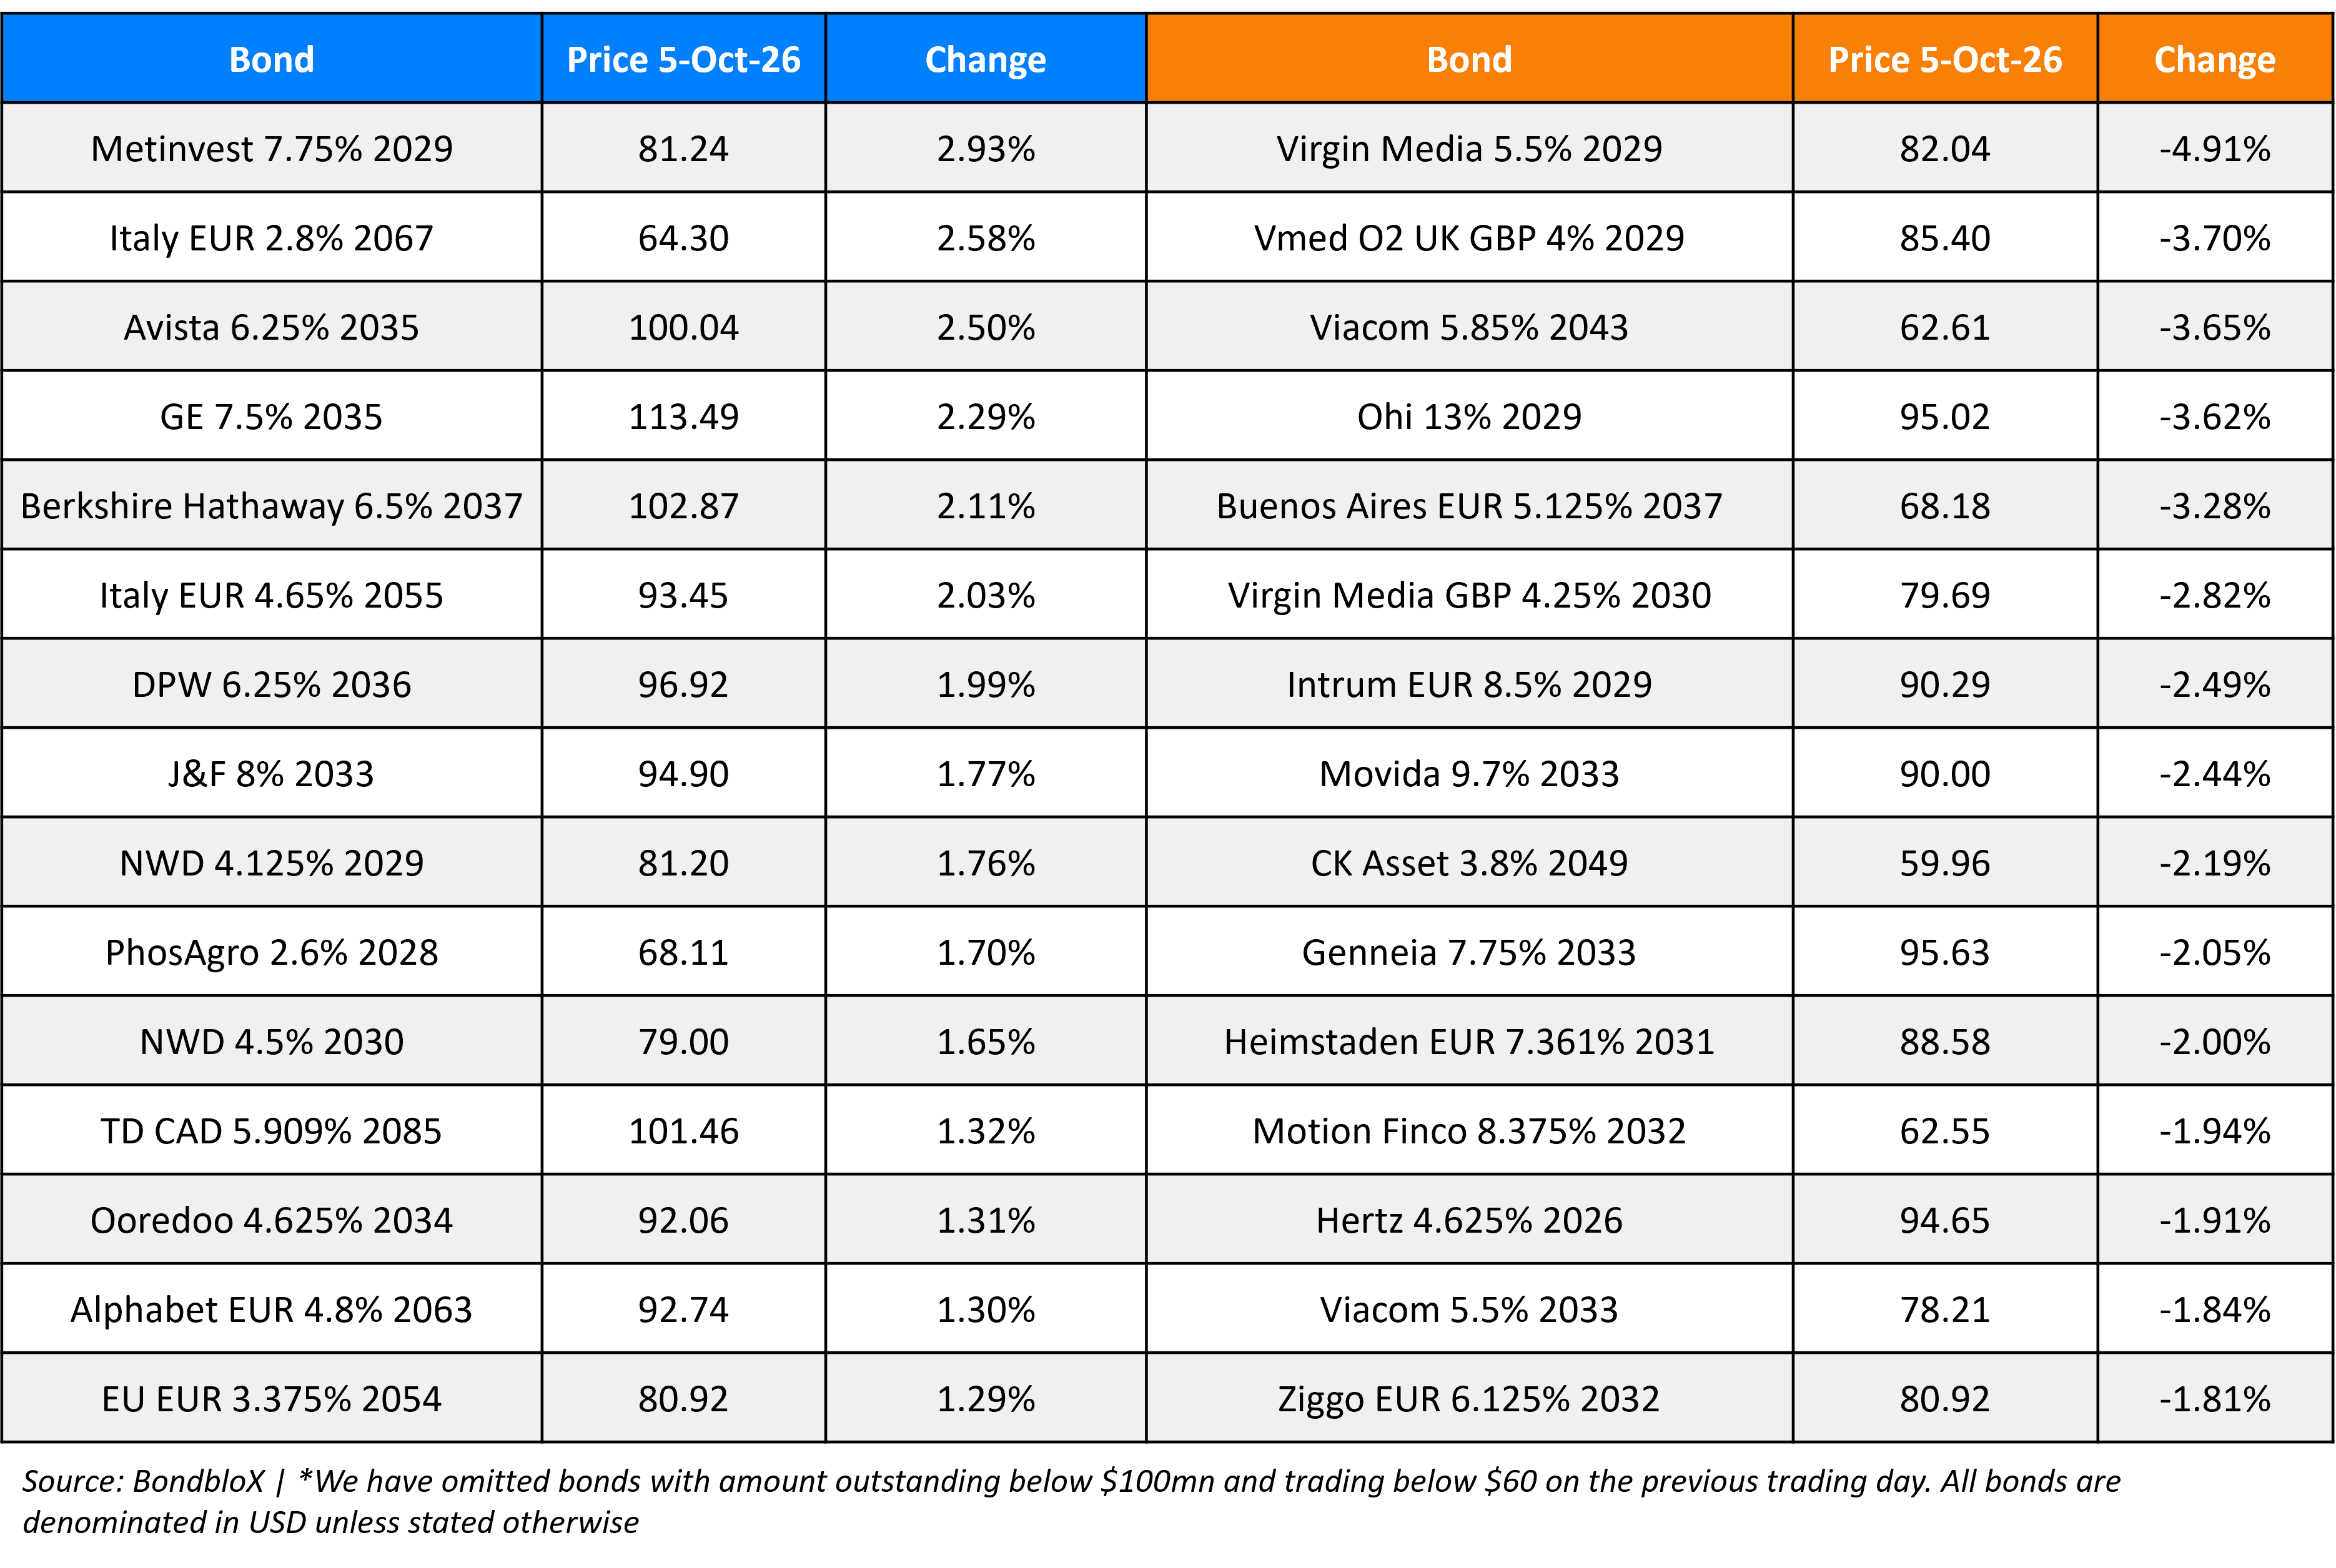
Top Gainers and Losers- 05-Oct-26*
Go back to Latest bond Market News
Related Posts: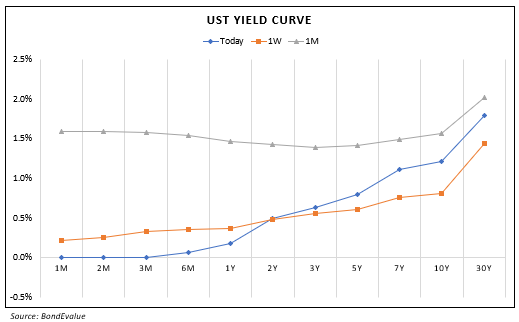
Our Awards
BondbloX Pte. Ltd. is regulated by the Monetary Authority of Singapore as a Recognised Market Operator ("RMO") and exempted from Section 49(1) of the Securities and Futures Act (Cap. 289) ("SFA") under Section 49(7) of the SFA.